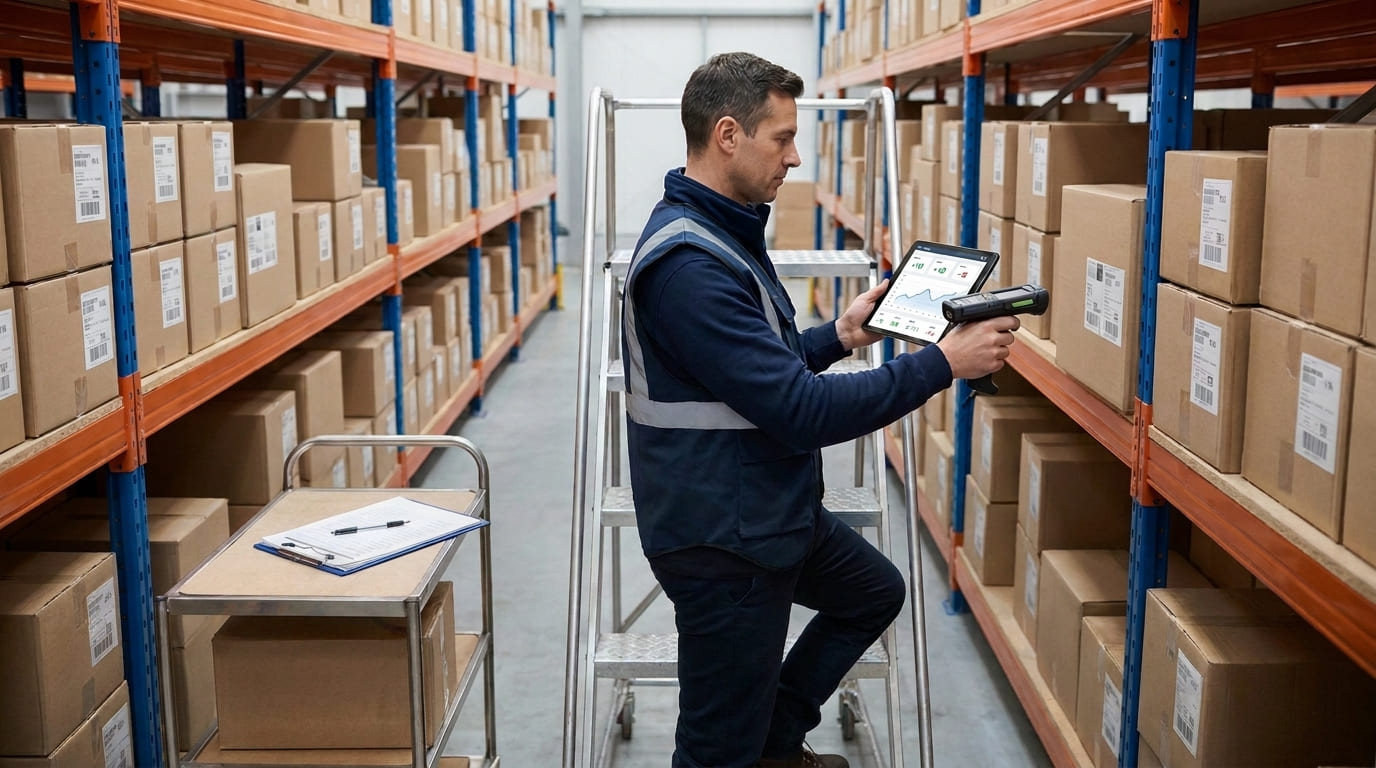
Inventory records do not always match the physical stock available in a warehouse or stockroom. Products can become damaged, expire, go missing, or be recorded incorrectly during receiving, picking and stock transfers. These differences create inventory discrepancies that businesses must investigate and correct.
Inventory adjustments help businesses maintain accurate stock quantities and financial records by documenting verified changes to inventory. However, making adjustments without proper investigation, authorization or supporting documentation can create additional errors and weaken inventory control.
Understanding when to make inventory adjustments and how to control them helps warehouse managers, inventory controllers and business owners reduce stock discrepancies, improve inventory accuracy and maintain reliable inventory records.
What Are Inventory Adjustments?
An inventory adjustment is a recorded change to the quantity, condition, availability or financial value of inventory to reflect verified stock information.
Businesses use inventory adjustments when physical inventory differs from recorded quantities or when the value of existing stock needs to be corrected.
For example, an inventory system might show 200 units of a product, but a physical count identifies only 194 usable units. After investigating the six-unit difference, the business can record an authorized negative inventory adjustment of six units.
Inventory adjustments generally involve:
Quantity adjustments: Increase or decrease recorded stock quantities.
Positive adjustments: Increase inventory when verified stock exceeds recorded quantities.
Negative adjustments: Decrease inventory when actual usable stock is lower than recorded quantities.
Value adjustments: Change the financial carrying value of inventory without necessarily changing its physical quantity.
Inventory write-offs: Remove unusable or lost inventory according to company policy and applicable accounting requirements.
These adjustments create a documented inventory transaction that helps maintain accurate stock balances and inventory movement history.
When Should You Make Inventory Adjustments?
Inventory adjustments should be made when an investigation confirms that recorded inventory information no longer reflects the actual quantity, condition or appropriate carrying value of stock.
Common situations include:
1. Physical Inventory Count Discrepancies
Physical inventory counts frequently reveal differences between recorded and actual stock quantities. These discrepancies can result from counting mistakes, unrecorded transactions, misplaced products or incorrect receiving records.
Before adjusting inventory, recount the affected items and review recent stock movements. Once the difference is verified, record the appropriate quantity adjustment with a clear reason.
2. Damaged or Defective Products
Products can become damaged during storage, transportation, handling or warehouse operations. Damaged items should be identified and separated from saleable inventory.
Record the affected quantities and document the reason for removing them from available stock. Depending on their condition, products may require repair, return, disposal or an inventory write-off.
3. Expired or Obsolete Inventory
Businesses dealing with food, cosmetics, pharmaceuticals and other time-sensitive products must monitor expiration dates and product usability.
Expired products should be removed from available inventory according to applicable procedures. Obsolete inventory may also require a value adjustment or write-down when its carrying amount is no longer recoverable.
4. Inventory Shrinkage, Theft or Loss
Inventory shrinkage occurs when recorded stock exceeds the actual quantity available. Common causes include theft, misplaced products, operational errors and unrecorded stock consumption.
Investigate the missing inventory before recording a negative adjustment. Document the confirmed shortage and retain relevant evidence for management review.
5. Data Entry and Receiving Errors
Incorrect quantities entered during receiving, returns or stock updates can create inaccurate inventory balances.
For example, recording 150 units instead of the 105 units actually received creates a 45-unit discrepancy. Review the original receiving documents and correct the source transaction whenever possible. Use an adjustment only when a separate inventory correction is appropriate.
6. Found or Previously Unrecorded Inventory
Sometimes employees discover products that are physically available but missing from inventory records. After verifying product identity, ownership and location, businesses can record an authorized positive adjustment to recognize the stock.
When Should You Avoid Making Inventory Adjustments?
Not every inventory discrepancy requires an adjustment. Sometimes the problem originates from an incomplete or incorrectly recorded transaction.
Avoid using inventory adjustments to hide:
Unposted purchase receipts.
Missing sales transactions.
Incorrect warehouse transfers.
Unrecorded customer returns.
Duplicate inventory entries.
Temporary differences caused by transaction timing.
Unresolved discrepancies that have not been physically verified.
For example, if a warehouse transfer has been dispatched but not received in the system, investigate and complete the transfer process instead of simply increasing stock at the destination.
The principle is simple: correct the original transaction whenever possible. Use an inventory adjustment to correct a verified inventory difference, not to conceal an operational error.
How to Make an Inventory Adjustment: A Step-by-Step Process
A standardized inventory adjustment process ensures that every correction is verified, documented and authorized.
Step 1: Conduct a Physical Inventory Count
Count the affected products and compare actual quantities with the inventory system. Use SKU identification, barcode scanning and location records to ensure that the correct items are counted.
Cycle counting can also help businesses identify discrepancies throughout the year without relying exclusively on annual physical inventory checks.
Step 2: Investigate the Discrepancy
Review recent purchases, sales, returns, transfers, receiving documents and stock movements. Determine whether the difference resulted from a counting error, damaged products, missing inventory or an unrecorded transaction.
Step 3: Identify the Adjustment Reason
Select an appropriate inventory adjustment reason code, such as damaged stock, physical count variance, confirmed loss or data correction.
Standardized reason codes help managers identify recurring problems and analyze inventory adjustment trends.
Step 4: Calculate the Adjustment
Compare the verified physical quantity with the recorded inventory balance.
For example:
The calculation is:
Adjustment = Physical quantity − Recorded quantity
194 − 200 = -6 units.
This represents a negative inventory adjustment of six units.
Step 5: Obtain Management Approval
Before posting an adjustment, follow the company's authorization policy. High-value products, substantial quantity differences and unusual inventory losses may require additional review.
The employee responsible for counting stock should ideally not have unrestricted authority to approve and post the same adjustment.
Step 6: Record the Adjustment
Document the SKU, product description, location, original quantity, adjusted quantity, reason code, date and responsible employee.
Attach supporting evidence, such as physical count sheets, photographs or receiving documents, when appropriate.
Step 7: Reconcile and Review Inventory Records
After posting the approved adjustment, verify the updated inventory balance. Review the inventory ledger and relevant accounting records to ensure that the correction is properly reflected.
Retain the adjustment history for future audits and management reporting.
8 Best Practices for Controlling Inventory Adjustments
Controlling inventory adjustments requires consistent procedures, employee accountability and reliable documentation.
1. Establish an inventory adjustment policy. Define when adjustments are permitted, who can create them and which situations require management approval.
2. Use standardized reason codes. Classify adjustments according to their actual causes, including damage, shrinkage, counting errors and found stock.
3. Set approval thresholds. Establish different authorization requirements based on adjustment quantity, financial value and inventory risk.
4. Separate employee responsibilities. Where practical, assign counting, recording and approval responsibilities to different employees to strengthen internal controls.
5. Maintain supporting documentation. Keep physical count sheets, adjustment references, photographs and transaction records to explain every correction.
6. Conduct regular cycle counts. Verify frequently moving, high-value and sensitive inventory to identify discrepancies before they become larger problems.
7. Maintain an inventory audit trail. Record who created, reviewed and approved each adjustment, including relevant dates and transaction details.
8. Monitor adjustment trends. Review adjustment frequency, inventory shrinkage, stock variance percentages and recurring discrepancies by product, employee and warehouse.
These controls help businesses identify operational weaknesses instead of repeatedly correcting the same inventory problems.
How Does Inventory Management Software Help Control Adjustments?
Managing inventory adjustments through disconnected spreadsheets and paper records can make it difficult to maintain accurate transaction histories.
Inventory management software helps centralize stock information, record inventory movements and improve visibility across storage locations.
For example, GearChain supports inventory tracking through customizable forms that allow businesses to record incoming stock, outgoing stock, transfers and count adjustments. Its inventory workflows support barcode identification and recording item names, quantities and locations.
Businesses can use barcode inventory tracking to identify products during stock verification and reduce manual identification errors.
For items without existing labels, manual inventory entry allows teams to capture product information and generate unique barcodes.
Multi-user inventory management also provides role-based permissions, helping businesses control who can view, edit or administer shared inventory records.
Additionally, multi-location inventory tracking helps businesses maintain visibility across different warehouses and operational sites.
For businesses using spreadsheets, inventory management software can help connect existing records with inventory tracking workflows.
These capabilities support inventory documentation, stock visibility and team coordination. Businesses should still establish their own adjustment approval policies, accounting procedures and verification requirements.
How Do Inventory Adjustments Affect Financial Records?
Inventory adjustments can affect both physical stock records and financial reporting.
A quantity adjustment may change the inventory asset balance and create a corresponding expense or other accounting entry, depending on the reason and applicable accounting policy.
For example, confirmed inventory shrinkage may require a reduction in the inventory asset balance and recognition of an appropriate expense.
Value adjustments are different. A write-down may reduce inventory's carrying value when its net realizable value falls below cost under the applicable accounting framework.
Inventory costing methods, including FIFO and weighted average cost, help determine the cost assigned to inventory. Businesses should apply their established costing and accounting policies consistently when recording financial adjustments.
Final Thoughts
Inventory adjustments are essential for maintaining accurate stock records, but every correction should have a clear reason, supporting evidence and appropriate authorization.
Businesses should investigate physical count discrepancies, document damaged or missing products, establish approval procedures and monitor recurring stock variances. Regular cycle counting and reliable inventory records can also reduce unnecessary adjustments.
By combining standardized inventory control procedures with barcode scanning and centralized inventory management, businesses can improve stock accuracy, strengthen accountability and maintain better control over inventory operations.
Frequently Asked Questions
1. What is an inventory adjustment?
An inventory adjustment is a recorded change to an item's quantity, availability status, or value so inventory records reflect verified conditions. Businesses use adjustments after investigating count differences, damage, expiry, loss, or other documented stock events.
2. How do you make an inventory adjustment?
Count the item, compare the physical quantity with the system balance, investigate the difference, select an accurate reason code, and obtain the required approval. Record the adjustment with supporting evidence, then reconcile the updated inventory records.
3. What are the reasons for inventory adjustments?
Common reasons include physical count variances, damaged or expired goods, confirmed theft or loss, unrecorded internal use, and verified data-entry errors. Each adjustment should identify the actual cause rather than use a vague correction label.
4. How do you adjust inventory after a stocktake?
Compare the verified stocktake result with the recorded balance for each SKU. Investigate material differences, check recent receipts and movements, document the reason, obtain authorization, and post the approved quantity change with its supporting count record.
5. What is the difference between a positive and negative inventory adjustment?
A positive inventory adjustment increases the recorded quantity, usually when verified stock exceeds the system balance. A negative adjustment decreases it when fewer usable units are physically available. Both require investigation and documentation before posting.
6. How do inventory adjustments affect financial statements?
Quantity adjustments can change the inventory asset balance and may affect an expense or cost account, depending on the reason and accounting policy. Value adjustments can reduce carrying value. Finance teams should review entries under the applicable accounting framework.